Articles & Questions
Every week I publish a fun new article on a money topic I think you’ll find interesting. I also answer a handful of reader questions. Subscribers to my newsletter get to see everything first — but you can browse some of my past articles & questions on this page.
My Best Articles
Not sure where to start? Below I’ve handpicked a few of my favourites. And if you like what you see, don’t forget to subscribe to my free newsletter to get new issues before anyone else!
Search Articles
Regrets
My five-year-old jumped out of the ute and nearly toppled over under the weight of his school bag.
A backpack almost as big as him.
Then he stopped and held out his hand, waiting for me to take him in.
“Mate, I’ve got a meeting”, I said. “Surely you can walk in on your own.”
My five-year-old jumped out of the ute and nearly toppled over under the weight of his school bag.
A backpack almost as big as him.
Then he stopped and held out his hand, waiting for me to take him in.
“Mate, I’ve got a meeting”, I said. “Surely you can walk in on your own.”
He just stood there with his hand out, so I grabbed it and hurried him across the schoolyard, checking my phone over his head the whole way.
He hung up his bag, kissed me on the cheek, and whispered, “I’ll miss you Dad”.
Then I was gone, thundering down the highway to Bendigo.
When I got to my parents’ place I walked straight past Mum at the door and into my old bedroom for a Zoom meeting. It ran overtime. I came out apologising, not for the first time.
“I’m late for a board meeting”, I said.
Dad just smiled. “Busy”, he said. Not a question. A statement.
ANU researchers have been asking us how satisfied we are with life since 2019. This year we scored ourselves 6.22 out of 10. That’s the lowest they've ever recorded. Lower even than during the lockdowns.
Nearly three in five of us reckon life was better fifty years ago. Fifty years ago! When Spam was something you put in your sanger, olive oil came from the chemist, and salad was a slice of tinned beetroot.
Life is tough right now. There’s the rising cost of, well, everything. Yet while we’re watching our wallets something else is quietly disappearing.
Time.
My old man is 78. I see him about once a month, so I did the maths (that’s what I do). If he makes 88, that’s a hundred-odd dinners left.
One hundred dinners.
My youngest still grips my hand and kisses me goodbye. My eldest ducks down in the car so his mates don’t spot him with his old man (which I make worse by blasting Johnny Cash’s ‘Ring of Fire’ in the school carpark).
I’ve got maybe a hundred drop-offs before that little hand stops reaching too. The funny thing is, my little bloke is letting go of my hand at the same time I’ve stopped reaching for Dad’s. (Though we shake now, like men do. Firm grip, two pumps, see you next month.)
So, given it’s Father’s Day, do yourself a favour and do your own maths. How many Sundays have you got left with your parents? How many drop-offs before your kid ducks down in the car? Whatever number you land on, it’s likely smaller than you thought … and it’s the only balance that never goes up.
One of these mornings will be the last one my youngest son reaches for me. I won’t know it when it happens. Neither will you. These are the good old days.
Happy Father’s Day!
Tread Your Own Path!
Your Questions & Answers
I’m Getting Scammed by My Teenage Son
The Ultimate Father’s Day Gift
A Long Shot that Landed
I’m Getting Scammed by My Teenage Son
Hi Scott,
Our son is 16 and regularly asks us for money for açai bowls, bubble tea, gym membership, movies and other non-essentials. Individually they’re not huge, but they add up. What concerns me more is he doesn’t seem motivated to get a casual job. I can get a text or a call at almost any time of day asking me to transfer money for whatever he wants next. Some days I feel like I’m being scammed by my own teenager.
We’re fortunate we can afford to give him spending money. I’m starting to wonder if that’s the problem. Are we teaching him that Mum and Dad are an ATM, rather than the link between working, earning, saving and spending?
I don’t want to be overly strict or turn money into a constant argument. Do we stop paying for the extras and push him to get a job? Or give him a fixed weekly allowance with clear boundaries about what we cover and what he funds?
Sandy
Hi Sandy,
By asking this you’ve just given me a Father’s Day gift!
The next text he sends, here’s what I want you to write back:
“No.”
No is a complete sentence in my house.
Sandy, your son sounds like a spoiled, entitled brat. Your job as parents is to knock that out of him.
You do that by setting three boundaries:
First, no more spending money.
Drawing that line will feel brutal. You’ll know how strong the boundary is by how much he flips out (the bigger the outburst, the better the boundary in my book).
Second, do not under any circumstances pay him an allowance, even if you dress it up as chores.
Why?
You’ll set up a transfer. He’ll do it for a fortnight, and then quit and keep pocketing your money.
Bugger that!
Third, don’t pay him to have manners.
While you’re straightening your spine, explain that he clears his dishes, cleans his room and does his laundry without getting paid. That’s what being in a family is. You all pitch in.
Sandy, the lesson he needs is simple:
Money comes from working.
If he wants açai bowls, movie tickets or a gym membership, he pays for it with a part-time job.
Draw the line and hold it.
The Ultimate Father’s Day Gift
Hi Scott
I’ve read your emails weekly for years, but only today felt the need to write to you and say thank you. My father passed away this morning at the age of 77 after a long fight with cancer. As I sit here typing this, I’m thinking about a column you wrote years ago for Father’s Day, where you suggested that one of the best gifts you can have is a video of your dad talking about his life, guided by five simple questions. We recorded that video back then. I’m watching it now, hearing his voice, listening to his stories – and while I miss him more than ever, I’m deeply grateful to have 45 minutes of him to return to whenever I need. That gift means more to me and my brothers than you can imagine.
Andrew
Hi Andrew
I’m so sorry for your loss.
I’m glad you sat down and made that video when you still could. Forty-five minutes of his voice and his stories is more than most people ever get, and it’s gold.
Now, for the rest of you … we run this every year. Here’s a tip. If your dad is still around, get your kids to do the interviewing. Less awkward for everyone, much cuter – and, after all, grandparents never say no to their grandkids.
Here are the questions:
How did you meet Mum?
What advice can you share with me about money, life and happiness?
What does being a dad mean to you?
What are you most proud of?
How would you like to be remembered?
Phone out. Hit record.
Andrew gave his dad a lifetime of Father’s Day presents. All of them are now forgotten. Except this one, which will be cherished forever.
A Long Shot that Landed
Scott,
I’m a single woman in my 50s, no kids, earning under $80,000. In 2017, on Dad’s advice, I started your book. I cut up the credit card, cleared the debts, boosted my super and opened a Mojo account.
When Dad was diagnosed with terminal cancer he made us a promise: Barefoot Date Nights. I’d read a step, we’d have dinner, he’d quiz me, and we’d tick it off together. It reassured him. It gave us time. But sadly we didn’t get to finish.
Now I’ve just received my own cancer diagnosis. Surgery and treatment mean unpaid leave, which is exactly what Mojo is for. Thanks to an inheritance, my apartment is paid off and I have $250,000 in the bank. I know how lucky that is. I’m grateful every day. I’m also scared about the next step. Shares confuse and frighten me. Writing to you is a long shot. I don’t expect a reply!
Gwen
Hi Gwen
Your old man would be proud of you.
Sitting down and doing the Barefoot Steps with your father was his way of sharing some precious time with you, and preparing you for life without him. And it worked. You’re facing a tough challenge, and financially you’re fighting fit.
Good work Dad. Good work Gwen.
You’ve earned the right not to stress about money right now. The share market can wait. Focus on your treatment. When you’re better, top the Mojo back up and put a bit extra into your low-cost super fund.
Finish the book when you’re ready. Tick off the last steps for him.
Thanks for reading,
Scott.
The best question this year
How cool is this?
On Tuesday an eight-year-old named Molly filled out the “Ask Barefoot” form on my website:
“My parents won’t allow me to buy shares, and it makes me feel so sad. Please help me! Molly”
How cool is this?
On Tuesday an eight-year-old named Molly filled out the “Ask Barefoot” form on my website:
“My parents won’t allow me to buy shares, and it makes me feel so sad. Please help me! Molly”
Molly could’ve been on Roblox. Or Netflix. Instead she’s on my website, asking about money.
(Under annual income she wrote: $100.)
Well Molly, you’ve shot to the top of my pile. By the end of this not only will you own your first shares… you and I will have taught your parents a lesson that changes their lives.
Here’s the thing about Mum and Dad. They’re probably a bit scared of the share market. Most adults are. Nobody taught them this at school, so it feels risky and confusing.
Your mission is to teach them… tonight, over dinner.
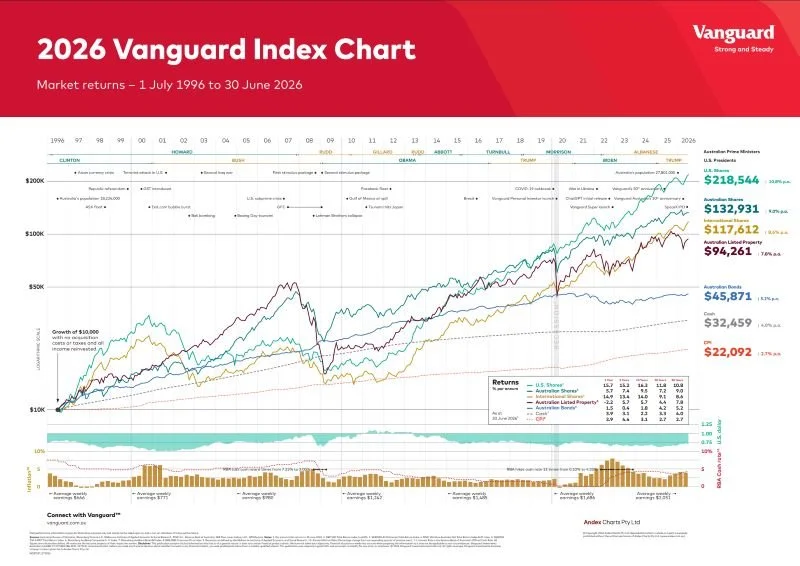
First, print off the 2026 Vanguard Index Chart. Google it. It’s free, and it’s the ‘Mona Lisa’ of money.
While you eat your broccoli, ask your parents:
“How old were you two 30 years ago?”
Chances are they were about your age.
Now show them the chart. It tracks what $10,000 in 1996 would be worth today if you’d invested it in different things.
Left in cash it becomes $32,459.
Put into Aussie shares, it becomes $132,931.
The difference? A hundred grand!
“But what if we invest and it crashes like your uncle Derrick is always warning about?” they’ll ask.
Great question. Let’s play a game.
Imagine you’re the unluckiest investor in the country. Vanguard actually ran the numbers on this.
You invest $10,000 into a mix of local and global index funds … right before the dot-com crash.
Another $10,000 … right before the Global Financial Crisis.
And the last $10,000 … right before Covid hits.
Every time, you buy at the absolute peak. Thirty grand at the three worst moments in a generation.
So how did you do?
Today it’s worth $117,000.
Yet if you kept it in cash it would only be worth $54,000.
(And let’s be honest, most of that cash would have disappeared on holidays, renovations, and “just this once” spending.)
The worst-timed investor in Australia still doubled the one who “played it safe”.
Yes, things went wrong. Covid. Dot-com. The GFC. Uncle Derrick will keep warning you about the next disaster until the day he dies. The trick is to look at what quietly went right.
You’ve done three things. You taught your parents something. You learned the best way to learn anything… by teaching it. And you flicked on the most powerful force in the universe: compound interest.
Google “Aussie investing apps for kids”, then get your parents to download one and buy some shares (called index funds) for you. You can start with as little as $5. And remind your parents they can invest some of their money too! Why should you have all the fun?
Before you ask to leave the table, ask one last question to make your parents squirm.
“How old will you be in 30 years?”
You’ll be 38, Molly. Wealthy. And only just getting started.
Your parents?
They’ll be pushing 70… still wondering if they should have started earlier.
The truth?
This was never a column about an eight-year-old.
It’s about you.
The one reading this on your phone, or in the paper, or while you’re meant to be doing something else. You’ve got the chart. You’ve got the proof. You’ve got an eight-year-old who’s already braver than most adults.
So what the hell are you waiting for?
Tread Your Own Path!
Your Questions & Answers
Paralysed with Fear
The $5 Million Accountant
Paralysed with Fear
Hi Scott,
I’m 42 years old. Two years ago my husband left, giving me 100% care of our two kids. We're immigrants with no family here. I was never allowed to handle our finances. Any question made him angry, as if I were attacking him. He earned $300k a year but still ran up $53k in credit card debt.
After the settlement I received around $400k. I stared at that number for months, paralysed. Then I read your book and put it into high-yield accounts. I now work part-time on a low wage, with single-parent tax benefits. My super is only $13k. His child support covers the rent on our one-bedroom unit. It's getting small as the kids grow, but they're in a great school and we've finally found community and belonging. I won't pull them out to save money.
I sit on the cash, because if the child support stops we have no way to survive. My only plan B is to buy a studio, so we have a roof. That means nothing for super, nothing for shares. Am I okay or am I crazy to just sit on it until the kids are old enough to be financially independent adults? It is about 25 years left for my 3 years old to be able to take care of himself.
Indra
Hi Indra,
You are not crazy.
You’re a single mum in a foreign land with no family and no backstop. You’ve suffered financial abuse and betrayal. So you chose safety for you and your kids. That makes complete sense to me.
Yet here’s the thing I want you to see. He’s still controlling you. You’re squeezing your family into a one-bedroom unit and sitting on $400,000 of your own money because you’re scared of what he might do.
Screw him.
That money is yours. Spend some of it on renting a place that actually fits your family. It doesn’t need to be flash, but it does need to be big enough that you live comfortably.
If you were my sister, here’s what I’d tell you.
Get yourself so damned secure you’re bulletproof.
You don’t have to solve the next 25 years today. Just take the next step.
For the next few years, your best return will come from investing in yourself. Get a qualification or training that moves you into higher-paid work.
I know what you’re thinking. As a single working parent there aren’t enough hours in the day. So use some of the money to buy time. A babysitter or a cleaner. Free yourself up to focus on building your career.
While you’re at it, sort out your super and make sure you have income protection, disability and life cover through the fund. Your super is the one thing that’s just for you. And you don’t have to carry the kids until they’re 28. Eighteen is enough.
Do this and in a few years your income will be growing. You’ll be able to buy a home of your own. And you’ll have the financial safety you need.
Indra, you may doubt that you can do this.
I have no doubts whatsoever.
You know why?
Because I see a woman with grit whose kids are in a great school, in a community where they belong. You did that.
Your kids are watching. They’re getting a masterclass in grit from the strongest person they know.
That’s the real inheritance.
You’ve got this.
The $5 Million Accountant
Scott,
My dad spent a lifetime building an accountancy practice and delivering sage, safe advice. When he sold his practice he was going through the emotional upheaval of retirement, but he didn't talk it out with a counsellor. Instead he got hooked by a highly sophisticated crypto scam, with a legit-appearing front.
He has handed over in excess of $5 million to them (details are not clear, he is very unwilling to divulge). This would be the proceeds from selling his business, and devastatingly, his house.
We thought he was out of it. He told us that he had received a sum back, and that he would secure his accommodation, but he's just started (again) asking for money. He thinks that a few thousandthousands would get him his money back. The whole family has urged him to report to the authorities and file for bankruptcy. I think he is too deeply in denial, as he's continuing to insist that he is not bankrupt.
Kate
Hi Kate,
That is absolutely horrific.
I’m so sorry this happened to your dad.
You said that your dad received a “sum back”. That’s the equivalent of a $1 pokie machine ‘winning’ 10 cents: they’ve already stolen $5 million from him. They won’t stop until he goes bankrupt. Even then they’ll keep going trying to squeeze the last few bucks out of him. I’ve seen them steal the insurance payout from a terminal brain cancer patient.
These people are evil.
More than 80% of Australians received at least one scam attempt in the last year, according to the ABS.
They’re so prevalent that we all know someone who’s lost money. Yet it’s not just the money that gets lost. People get robbed of their sense of self worth … and they often lose their will to live.
Your father needs proper support and counselling right now, and more than ever. The money is gone. What matters is that he’s still here. That’s the one thing left to protect.
The only way you can defeat evil is with unconditional love.
Thanks for reading,
Scott.
Barefoot Bubbles
My son Odin absolutely loves Barefoot Kids – he’s followed every single step over the past year.
My son Odin absolutely loves Barefoot Kids – he’s followed every single step over the past year. He’s even started his own little business making and selling bubble kits! Would you be willing to check out his video and let us know what you think?
Thanks so much,
Proud Parent
Hello Proud Parent,
Because I am fiercely independent, I cannot endorse products. However, I showed my kids Odin’s video and now they are pestering me to buy one of his bubble kits!
He’s a natural salesman, congrats!
Scott
Slim Dusty and the Nine-Year-Old
Dear Scott,
My name is Imogen. I’m nine years old and live in Melbourne. I was camping with my country cousins at Christmas when my uncle made me a deal: he’d give me $50 if I could learn and recite one of his favourite Slim Dusty songs.
Dear Scott,
My name is Imogen. I’m nine years old and live in Melbourne. I was camping with my country cousins at Christmas when my uncle made me a deal: he’d give me $50 if I could learn and recite one of his favourite Slim Dusty songs.
It’s a poem by Henry Lawson called ‘Peter Anderson & Co’. I had to recite it by heart by 10 January 2025. It was tricky at first, but I got there – and I won the $50! (I gave my little sister $10 because she helped me.) My uncle said I should invest the rest. Scott, do you have any ideas for what company I could own a share in? I love animals! Please could you write back with some ideas? My mum reads your column – maybe you could put your suggestions in there? Also, I’ve read Barefoot Kids – it’s the best!
Imogen
Hey Imogen,
I’d never heard of the song, so I looked up the lyrics. They went for three pages (!), with lines like:
See if you can raise a drink, old man, I’m feelin’ mighty bad
Hot and sweetened, nip o’ butter, squeeze o’ lemon, Pete, he sighed.
That’s just weird!
Yet good on you for memorising it – you certainly earned your pineapple.
So here’s what I think you should do with your forty bucks.
First, given your love of animals, I think you should donate $10 to a local animal shelter or the RSPCA. Even $10 can help buy two warm blankets for a puppy, cover food for a cat for nearly a week, or pay for a microchip that helps a lost pet find its way home.
Second, ask your parents (or your uncle) to help you google “kids’ investing apps”. Plenty of them let you start with just a few bucks, so you can use your other $30 to invest in Aussie shares. That’s right: you’ll own a slice of a real company – like Woolies, Coles and the banks.
Pretty grown-up stuff.
And you know what’s cool about that?
You’re memorising this stuff when you’re nine – most people don’t hear the tune until they’re 59. You are going to be so wealthy. I can feel it.
Finally, your uncle sounds like a fun guy. Why not challenge him back? If he can memorise Taylor Swift’s ‘Shake It Off’, tell him you’ll give him $1!
Scott
An 11-Year-Old With a BIG Problem
I’m 11 years old and I’m trying to invest, but I’m having a problem. Every investing app I try has monthly fees up to $10 a month! Can you please help give me some advice on how to find the right investing app.
Hi Scott,
I’m 11 years old and I’m trying to invest, but I’m having a problem. Every investing app I try has monthly fees up to $10 a month! Can you please help give me some advice on how to find the right investing app.
Emery
Hi Emery
Mate, this is a very impressive ‘problem’ for an 11-year-old to have!
Most kids your age are picking their noses or gambling on Roblox, but you’re not just considering investing, you’re asking the right questions too!
Yes, fees suck, especially when you’re only investing small amounts.
So, here’s what I want you to do:
First, figure out how much you plan on investing. Maybe it’s $100 to start with, then $50 a month.
Then I want you to google the following apps: Pearler Micro, Vanguard (accounts for kids), Raiz and CommSec Pocket, and work out how much each of these apps would cost in fees to invest in a high-growth shares option.
Finally, show your workings to your parents – I’m sure they’ll be impressed. Then ask them to cover your fees for the first year!
Remember, investing is like planting a little apple tree. You’re doing the hard work by planting it in good soil now, then you can sit back and watch it grow. Enjoy the apples. Spit out the pips.
Scott.
No Batteries Required
We got both my boys the Barefoot Kids book for Christmas over a year ago. In the last four months, Charlie has made over $100 from recycling cans and bottles. Charlie and our eldest son, Patrick, who’s 11, have also begun buying and selling Pokemon cards on eBay!
Hi Scott,
We got both my boys the Barefoot Kids book for Christmas over a year ago. In the last four months, Charlie has made over $100 from recycling cans and bottles. Charlie and our eldest son, Patrick, who’s 11, have also begun buying and selling Pokemon cards on eBay! Understanding how to make money, appreciating it, showing gratitude for their situation, sharing and being kind are ongoing lessons. Thanks for writing and sharing your books!
Peter
Hi Peter
Please pass on the following message to Charlie and Patrick:
Boys, good work on the little business you’ve got going. I’m really proud of you!
Now, there are still a couple of weeks before Christmas, and I’ve got another challenge for you:
I want you to take some of that money you’ve earned and buy some nice presents.
First, for your mum and dad, and brothers and sisters.
Then I want you to go to Kmart and buy a gift for a little kid your age – it could be a book (Barefoot Kids?!), stickers or something else awesome – and then place it under the tree in the store.
You’ll be a Secret Santa for someone who really needs it.
Merry Christmas!
Peter, thanks so much for giving me the perfect opportunity to plug Barefoot Kids for Christmas. There’s something really quite magical about that book. Kids devour it and then go off and do awesome things that make their parents (and grandparents) proud.
-Scott.
My Parents Don’t Support Me
My name is Laura and I’m 12 years old. A couple of months ago I was given a copy of Barefoot Kids. I’ve come to inform you that I’ve read it many times and it has inspired me to become a better person when it comes to money.
Hi Scott,
My name is Laura and I’m 12 years old. A couple of months ago I was given a copy of Barefoot Kids. I’ve come to inform you that I’ve read it many times and it has inspired me to become a better person when it comes to money. But I have one problem: how can I convince my parents to let me go ahead with my money-making schemes? I write down plans, and I do a bit of a presentation, and I do research, but nothing works. My parents own their own small and successful business, which is why I have always wanted to be an entrepreneur myself. I get that they would rather me starting small and helping out with their business, but all I dream of is owning my own. Please help!
Laura
Hi Laura
Right now, there are thousands of parents who have just read your question and their mouths are as wide open as Joe Biden’s (and they also have the same dumbfounded look on their faces).
Here’s why: all that most parents get with their tweens is grunting, slamming doors, and eye-rolls … lots of eye-rolls.
You, on the other hand, are doing research and presentations, and pleading with your parents for their approval to let you use your initiative to work hard, learn, make money and grow as a person.
Some parents don’t know how good they’ve got it.
Here’s what I want you to do: put this under their nose. It doesn’t matter if they read my answer – it’s your question that I want them to read. After all, you said that they are your inspiration for wanting to become an entrepreneur.
Sweet Baby Jesus!
If any of my kids said that to me, I’d be a blubbering mess. That’s what every parent dreams of!
And after that, if they still don’t want to help you, I will.
Good luck.
Scott.
Chop Wood, Carry Water
We confiscated our 14-year-old son’s phone over a year ago because he was misusing it. It’s been a long year of self-harm and reminding him he is supported and loved.
Dear Scott,
We confiscated our 14-year-old son’s phone over a year ago because he was misusing it. It’s been a long year of self-harm and reminding him he is supported and loved. It’s now time for him to get one again, primarily to check in with us when he’s away. So here’s the argument I’m having with my hubby: I want him to earn the phone – we have five acres of bush and I have the idea that he only needs to sell one bag of firewood a month to pay for a phone. My hubby says it isn’t worth the cost of petrol, chainsaw, and delivering the wood to customers. He just flat out says “no, it’s spending money to make money”. He won’t be reasoned with at all. Help!
Linda
Hi Linda,
Your husband may not show it, but I’m sure he’s been worried sick about your son self-harming.
Any parent would.
So here’s how I’d approach it with your husband:
Ask him to think about how he’d feel as he watched your son start his own little firewood business.
Paint him a picture:
He’d be off the screens and out into the fresh air, doing some physically demanding work. He’d be smiling and interacting politely with his customers. And, most importantly, his confidence would soar as he earnt his own dough.
Personally, I think this could work out to be the best money you and your husband ever spent. However, if it makes him feel better, you could write an agreement with your son that he has to pay you a certain percentage of each sale to cover the costs.
I think if your husband could see your son making a go of it he’d beam with pride.
Any parent would.
Scott.
New Vanguard Kids’ Account
Vanguard has recently released a new product, the Personal Investor Kids account. It starts with as little as $25 and offers a regular savings plan.
Hi Scott,
Vanguard has recently released a new product, the Personal Investor Kids account. It starts with as little as $25 and offers a regular savings plan. However, Vanguard ETFs are not available within the account, only their managed index funds. Considering that managed funds are generally outperformed by ETFs, is it still worth creating an account for my five-year-old son?
Lina
Hi Lina,
Your question makes me feel like I’m at the breakfast table at 5am.
It’s like you’re my two-year-old arguing that his Wheaties taste better in his favourite Bluey bowl. (I’ve had this argument way too many times.)
Lina, you are buying exactly the same index, and the exact same stocks. In fact, Jack Bogle (who founded Vanguard and pioneered index funds) favours managed index funds over ETFs, as they are less prone to trading.
What matters is that you invest. And that you then casually reinforce the investing lesson by reminding your five-year-old of all the companies he owns shares in (“You’re a part-owner in Woolies … and Coles … and Macca’s!).
Go on, plant that apple tree!
Scott.
Rich Kid, Poor Kid … Worried Mum
We have twin girls and we recently went all in on the Barefoot pocket money strategy.
Hi Scott
We have twin girls and we recently went all in on the Barefoot pocket money strategy. One of the twins is highly motivated when it comes to jobs and earning her pocket money, while the other doesn’t care for it at all. Like AT ALL! Her ‘currency’ is connections, not money. She barely gets any pocket money each week and we’re not making up the difference, but she still doesn't care. What do you do when financial or future motivation is not an incentive for a kid?
Worried mum
Hello!
So you have a kid who isn’t materialistic in the slightest and values people over money?
Sounds like an awesome kid to me!
Here’s what I’ve learned: lecturing and hassling your kids doesn’t work.
That’s why my brand new book (due out in November) is written directly for kids.
I gave a review copy to a kid who sounds exactly like your daughter. He’s not motivated by money at all … yet he read it cover to cover and started plotting out his own small business, not to buy stuff, but to donate to Foodbank.’
Scott.
Help me, help them
I’m a teacher, and I have an opportunity to put together a short finance course (10 lessons) for a Year 10 cohort at my school. I want to focus on how to set them up with really achievable, totally practical and easily applied approaches for future financial security.
Hi Scott,
I’m a teacher, and I have an opportunity to put together a short finance course (10 lessons) for a Year 10 cohort at my school. I want to focus on how to set them up with really achievable, totally practical and easily applied approaches for future financial security. There’s so much I want them to understand and so little time. What do you feel are the most critical lessons our teenagers need right now for the years ahead?
Sandra
Hi Sandra,
Kids don’t learn by lectures, but by rolling up their sleeves and doing stuff.
That’s why a few years ago I came up with my Barefoot Ten, which are ten things every kid should do before moving out. And since you need ten lessons, they could be useful inspiration. Here they are:
1. Open a zero-fee, high-interest saving account.
2. Buy and sell something second-hand.
3. Learn to cook at least two low-cost delicious, nutritious meals from scratch.
4. Volunteer in their local community.
5. Save their parents at least $100 on your household bills.
6. Promise to never, ever get a credit card.
7. Get a part-time job from age 15.
8. Earn at least one glowing reference from a boss.
9. Open up an ultra-low cost, high-growth super fund.
10. Set up a savings account for a home deposit (and nickname it even with a buck),
Feel free to steal these or create some of your own.
And if there are any primary school teachers reading … I have a book coming out in November that starts kids really early. I’ve just put the finishing touches on it. After I handed it to my editor, he said:
“This is the best book you’ve ever written.”
Scott.
You Have ZERO Credibility, Barefoot
Both my sons (age 13 and 15) have read your books and are practising the ‘Buckets’ strategy. They are slowly, slowly building their wealth to financial independence using earnings from weekend chores, part-time jobs and compound interest.
Scott,
Both my sons (age 13 and 15) have read your books and are practising the ‘Buckets’ strategy. They are slowly, slowly building their wealth to financial independence using earnings from weekend chores, part-time jobs and compound interest. However, I now question your credibility and moral compass. Your misguided publication of your cringe-worthy response to the unbelievable letter claiming “my hard-working 13-year-old has saved $200,000” has left me flabbergasted. Was this a joke? What 13-year-old saves $200,000? Hardworking? Probably. Lucky and the beneficiary of an inheritance or family trust fund? Definitely. This is a slap in the face to every Aussie battler. Sadly, Scott, you have lost a reader here.
Anthony
Hi Anthony,
Congratulations, you have won my reader ‘spray of the year’ award!
So the kid in question did make the $200,000 on their own … they’re actually in the entertainment business. (However, at the parents’ request I’m not being any more specific than that.)
Yet the real issue here isn’t with the kid, it’s with you.
It sounds like you have a lot of hang-ups about wealth. Now, Anthony, your concrete is set, and you’re unlikely to change. But you don’t want your sons to inherit your anger-envy. After all, it’s totally unproductive.
Fact is, they’re going to meet wealthy people who’ve gotten money from their family. That’s life. Not everyone is equal. Not even you. (Just try comparing your salary to an average Indonesian’s.) But your sons can control one thing: the amount of effort they put in.
Scott.
I Tried CommBank’s New App
A mate of mine is a fireman … so his kids get to ride in his fire engine and even get to blast the siren.I’m a finance guy, so my kids get to … beta-test the new Commonwealth Bank app for kids.
A mate of mine is a fireman … so his kids get to ride in his fire engine and even get to blast the siren.
I’m a finance guy, so my kids get to … beta-test the new Commonwealth Bank app for kids.
“Nee-Naw-Nee-Naw, our dad has the most boring job on the planet!”
(Yes, kids, but it pays the bills!)
Seriously, though, last week I received an invitation to venture deep into enemy territory — CommBank HQ! I think it’s fair to say that we haven’t seen eye to eye in the past (and I may have had a bit to do with culling their 90-year-old school banking program, the Dollarmites). Yet they still invited me for a sneak peek of their new pocketmoney app.
They’re calling it KIT, which stands for Keep In Touch (with your money). KIT is basically CommBank’s answer to the NAB-backed Spriggy. Yet there’s one really important difference: whereas Spriggy is designed for parents, KIT is designed for kids. (In fact, there is no ‘parent wallet’, other than a secret code for parents to pay their kids’ money.) I think this is actually really smart.
Do I think apps like this are going to change the pocketmoney game?
Maybe.
Then again, we still mainly use jam jars with our kids. After all, kids are visual … and I don’t have to remember any passwords or pay expensive annual fees for kid apps.
Still, I’ve committed to having the kids be part of the beta test and give their thoughts. I think they’ll enjoy it … if only because they rarely get to play on a screen. (I reckon I could load up a CommBank Annual Report on an iPad and they’d sit there swiping at it for hours.)
Stay tuned.
Tread Your Own Path!
Help! The Tax Man is Beating Up My Kid
I have a very hardworking 13-year-old who has amassed quite a bit of money: she has saved up $200,000!
Hi Scott,
I have a very hardworking 13-year-old who has amassed quite a bit of money: she has saved up $200,000! She would like to purchase a property but as a minor she will have to pay 66% on any income earned from the property. (Clearly she’ll still live at home until she’s old enough!) The goal is to own it outright in a few years and invest in more property, but I’m way out of my depth here. What is the best way for a minor like her to make their money work for them until they turn 18 — in their own name, not mine?
Helen
Hi Helen
Two hundred grand? That’s amazing! You must be very proud (and a fine role model).
You’re right about the penalty rate on kids under the age of 18 – however, this only applies to unearned income, like a bank account, rent or dividends from shares. It does not apply to income from the sweat of their own brow.
I wouldn’t limit your research just to property. It would be a good idea for her to learn about investing in the share market as well. To kick off her portfolio, all you’d need to do is set up an account as trustee for your daughter and purchase a hands-off portfolio of local and international shares. You’ll need to pay tax on the dividends – though franking credits mean it’s not much of an issue. To minimise this, open the account in the lower-earning spouse’s name. Then the shares can be transferred to her when she turns 18.
Finally, I’d give her my book (or audiobook) so she can learn all about investing and how to manage her money, as she seems to have the earning part all worked out!
Scott.
I’m All Ears
My 9-year-old daughter started a business making earrings and hair ties last year during lockdown. It’s grown so much in the last year she now has a few thousand dollars in her bank account!
Hi Scott,
My nine-year-old daughter started a business making earrings and hair-ties last year during lockdown. It’s grown so much she now has a few thousand dollars in her bank account! We have an agreement that she must split the money into reinvesting in her business, saving for the future, and saving for a short-term goal like an iPad (which she actually brought at the end of last year as a reward for hard work). Given the rate her business is going, I’d like to help set her up more for the future, but I’m not sure how to go about it, as I’ve never done this myself. I’m probably not the best role model for money with her. Can you provide any advice?
Tammy
Hi Tammy
Oh I LOVE THIS.
Let me tell you a little secret: you don’t need to know all the answers.
As parents we feel like we should, yet it’s usually better to work alongside your kids and help them work it out themselves. This is exactly what my next book is about. And I’d like your daughter to be a part of it!
So I’ll put my hand up to be both a customer (my wife likes earrings) and her financial coach.
I’ll be in contact next week.
Scott.
The Seven-Year-Old Financial Advisor
I am a seven-year-old who lives in Tasmania. I have read all your books and shared them with my mum.
Dear Scott,
I am a seven-year-old who lives in Tasmania. I have read all your books and shared them with my mum. This is helping her pay her debts, and I will make sure she gets a super account. I own a small business (for pocket money) but I don’t know the business laws and I would like it if you wrote a book on what you can and can’t do in business.
Michael
Hi Michael,
Thank you for sharing my books with your mum, and for nagging her to set up a low-cost super fund.
You’re a good son!
In terms of writing a business book for kids, well, I’ll let you in on a little secret:
I’m writing one.
Late last year, my son, who’s roughly the same age as you (you two would get along so well), started asking me lots of questions about setting up his own business.
We had so much fun discussing it, I decided to write a book about it.
Watch this space.
Scott.
My Son is a TikTok Star
My 15-year-old son owes a lot to homeschooling. He became super creative and started a TikTok profile @tcezy uploading weird, dark and mysterious content. He has amassed a huge 5.7 million followers in just over a year.
Hi Scott,
My 15-year-old son owes a lot to homeschooling. He became super creative and started a TikTok profile @tcezy uploading weird, dark and mysterious content. He has amassed a huge 5.7 million followers in just over a year.
We get daily emails from all sorts of companies wanting him to promote something but so far he has only agreed to one and it made him a staggering $10,000 . Now that could be it. But for the moment what should he do with it?
Jackie
Hi Jackie
So I just spent way, way, way too long watching your son’s videos.
Then again, that’s the point right?
He’s got more engagement than any prime-time television show, and unlike the idiot box, his ads won’t be a signal to duck off to the dunny.
In other words, this is a genuine business (though his business partner is a super creepy Chinese Artificial Intelligence company that is manipulating its users).
Still, if your son can continue creating great content he’ll have hit the jackpot: a well-paid job he’d gladly do for free!
As for what to do with the $10,000, I’d ask him to think about his saving goals:
Will he want a car in a few years?
If so, he’s better off saving it in an online saver.
However, I’d encourage him to invest the bulk of it in shares (there’s plenty of apps that can do it at a low cost), and only check the price every few years.
What an adventure. You should be proud!
Scott.
Thanks From Spider-Man
Here is a pic of my five-year-old, who started the Jam Jars last year and saved up enough to replace his broken Garmin band (he accidentally cut it with scissors at school last week) with a Spider-Man band. He received a double-edged lesson in saving AND in looking after his things.
Hi Scott,
Here is a pic of my five-year-old, who started the Jam Jars last year and saved up enough to replace his broken Garmin band (he accidentally cut it with scissors at school last week) with a Spider-Man band. He received a double-edged lesson in saving AND in looking after his things.
I read both The Barefoot Investor and The Barefoot Investor for Families a year after becoming a single mum. You revolutionised the way I conceptualise saving and I’ve since gone on to buy a house and build up my Mojo. “Don’t spend more than you earn.” It’s such a simple lesson, yet it’s not a lesson I was ever taught growing up.
Lisa

Hi Lisa,
What a little champion! This is the reason I came up with the Money Movement — I want this for every Aussie kid. You made my day.
Scott.
The ASX Game
My daughter recently brought home a consent form for me to sign. She is in Year 12 and, as part of Pathways and Wellbeing (PAW) this semester, the students are learning about investing in shares by playing the ASX Sharemarket Game. They are given $50,000 virtual money to invest over a 10-week period. Since reading your book in 2020, I have been investing in the ASX but not trading. My concern is that it is not focusing on long-term investment. So should I sign the form?
Dear Scott,
My daughter recently brought home a consent form for me to sign. She is in Year 12 and, as part of Pathways and Wellbeing (PAW) this semester, the students are learning about investing in shares by playing the ASX Sharemarket Game. They are given $50,000 virtual money to invest over a 10-week period. Since reading your book in 2020, I have been investing in the ASX but not trading. My concern is that it is not focusing on long-term investment. So should I sign the form?
Meg
Hi Meg,
Yes, you should sign the form!
This sounds like fun … and I think your daughter will end up a winner.
Do you know why?
Because she’s going to have a secret helper with the ASX game:
Me!
Here’s how I’d suggest she plays:
Put $25,000 in the Vanguard Australian Shares Index ETF (ASX code: VAS). Or, if she prefers a greener option, the Vanguard Ethically Conscious Australian Shares ETF (ASX code: VETH).
Then put $25,000 in the Vanguard MSCI Index International Shares ETF (ASX code: VGS). Or, again, if she wants a sustainable option, try the Vanguard Ethically Conscious International Shares Index ETF (ASX code: VESG).
With those two investments she’ll own shares in the largest companies in Australia and the world, and all for rock-bottom fees. She can school her teacher and explain that the overwhelming evidence suggests that she’s all but guaranteed to outperform her stock-picking pals over the long run (though I’m talking years ... not weeks).
Then she can use the next 10 weeks to read The Barefoot Investor. In fact, I’ll donate a signed copy to the school library!
Scott.
Reminder: I first wrote about this years ago and highlighted the low costs. Today there are better deals on offer. How do I know? Because my readers constantly email me about them! So before you do anything, do a quick google.
The Money Movement Manifesto
Over the past few years, I’ve been on a bit of a journey, and today I’d like to talk to you about it.
To be blunt, I see a lot of trouble brewing:
The rich are getting much richer … while the young, and the poor … are mostly not getting anywhere.
Over the past few years, I’ve been on a bit of a journey, and today I’d like to talk to you about it.
To be blunt, I see a lot of trouble brewing:
The rich are getting much richer … while the young, and the poor … are mostly not getting anywhere.
And I say that as a rich guy.
Yet I also say it as a volunteer financial counsellor. I regularly find myself sitting across from hardworking people helping them create budgets that round down to the dollar (as in we literally talk about $3 purchases).
The guts of it is this: the current zero interest rate policy favours the rich who own assets, and it penalises the poor … and young couples trying to save for their first home. They’re falling behind. And it’s only getting worse.
I’ve been thinking about this a lot.
Now, I’m not some do-gooder. And I’m not the smartest guy. And I certainly don’t have all the answers. Yet it seems to me that one of the most practical ways to at least try and balance out the scales of inequality is to teach kids the rules of the game.
How do you do that?
Well, not by theory, droning on to kids about stuff that isn’t relevant to their life right now. Which is why I created programs that got kids to roll up their sleeves and experience something, whether it be going home and teaching their parents about pocket money (in primary school), or landing a part-time job and saving up for something on their bucket list (in high school).
I didn’t get it right all the time. In truth, I stuffed it up many times (and thankfully I had a documentary crew capturing them). Yet in the back of my mind was the idea that many young people will have the financial odds stacked against them, so they need to know how the financial game is played — or it will be played against them.
That’s what the Money Movement is about. Based on my experiences in schools around the country, I’ve put together a manifesto which I plan to present to state governments around Australia.
So this week, I’m interrupting normal programming to ask a favour of you.
Have a read below and, if you agree, it would mean a lot to me if you’d digitally sign my petition.
The Money Movement Manifesto
Our kids will be tested on money skills every single day of their lives.
Yet most of us had to learn these skills the hard way, because we were never taught them in school.
We need to do more.
Here are the five core aims of the Money Movement:
Implement a practical 4-to-6-week Money Challenge every year
When literacy rates were falling, the Premier’s Reading Challenge was set up to challenge kids to read — and it worked! In the same way I’m calling on state governments to get behind a Money Challenge — not just another requirement in an already overcrowded curriculum, but something exciting that schools take up because it’s important, and fun!Show primary schoolers the power of working, saving, spending and giving
Get kids excited and it’s amazing what can happen. During a pilot Money Challenge at a school in Hervey Bay (one of the poorer regions in the nation), the six-year-olds came up with the idea of using their class ‘Give’ money to feed homeless people in their community. It was a life-changing experience for them — and for their community.Show high schoolers how to get a job and set up their savings ‘buckets’
You remember being a teenager in class thinking “How will I ever use this in the real world?” Well, at a pilot Money Challenge, I saw teenagers who were the first people in their family to get a job and set up their savings buckets. Think what your life would be like if someone had helped you do that on your first payday. I want that for every Australian kid. Let’s set them up to win.Commit to professional development financial education for teachers
Teachers aren’t in the job just for the money: it’s a vocation. Still, it’s hard to stand up in front of a crowd of year 9s and talk about the dangers of credit cards when you have credit card debt yourself. Bottom line: to raise financial fit kids, we need financially fit teachers.Kick the banks out of our schools
Having banks teach our kids about money is like having Ronald McDonald teach them about nutrition. Our children’s financial education is too important to outsource. The government financial regulator (ASIC) is independent of commercial interests and should be the one to deliver the program.
This is something I truly believe in, and I’ve been working on it — and piloting it in schools — for years. But now it’s time to take the next step and get your state government to take it on board.
I want every Aussie kid to learn this. If you do too, then I’d like to ask a favour:
Please visit change.org/money-movement and join the movement.
It’s free. It will take 30 seconds. I don’t want your money, just your signature.
Together we can teach the kids … help the parents … and change the nation.
Tread Your Own Path!
Scott.
P.S. For the record, I’m committed to working with any government that agrees to take this on — and I’ll offer my time and expertise for free.
P.P.S. I only need your signature NOT your money (Change.org may ask you for money to promote the petition, but that is not needed. Just say 'no').
Again that website is:
change.org/money-movement
Thank you.